Powering Payroll, Compliance & Workforce Management in Sweden

Expand with confidence. Get local employment and payroll guidance backed by 30 years of experience.
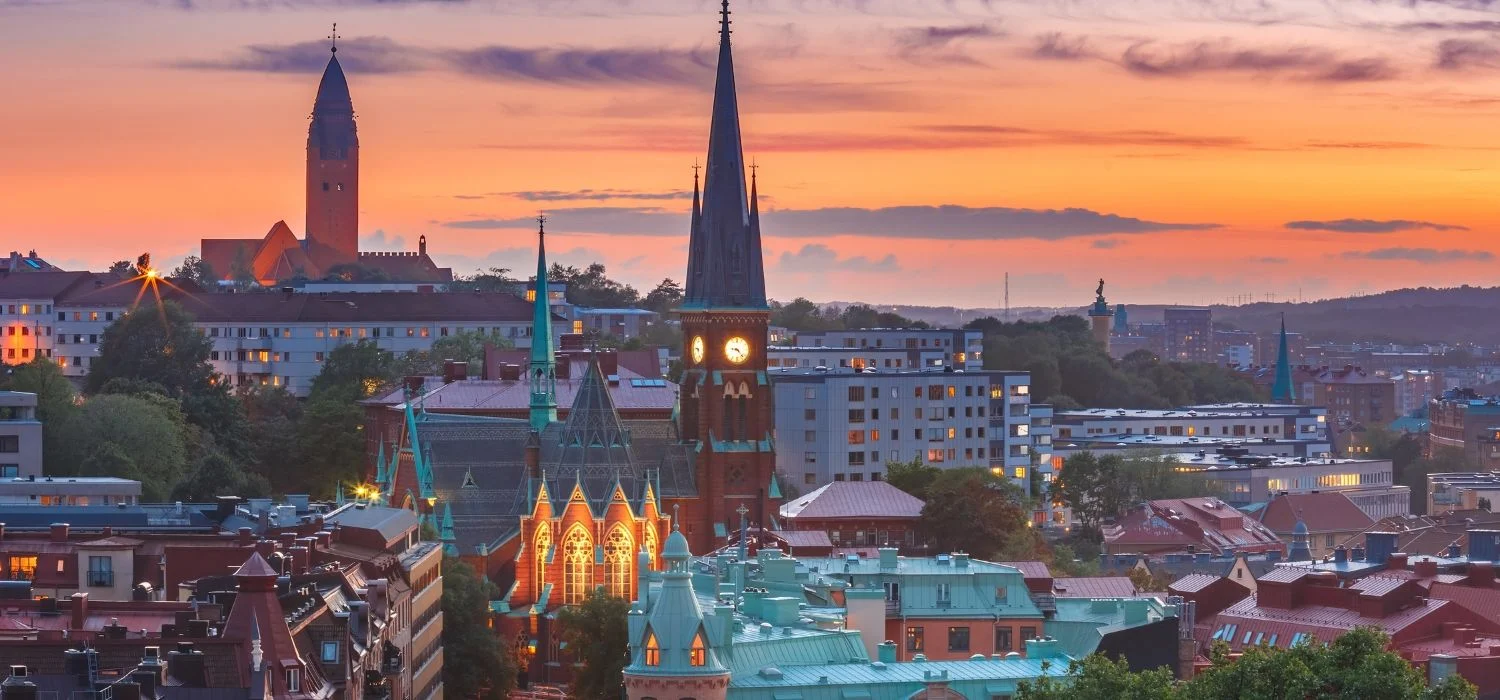
Sweden at a Glance

Whether you're hiring your first employee or expanding an existing team, understanding the local employment landscape is essential. From visa requirements and statutory benefits to payroll taxes and regulatory oversight, this section provides a practical overview of what employers need to know to stay compliant and operate effectively in 

Sweden
Work Permits & Visas
  • EU/EEA and Swiss citizens: Generally have the right to work in Sweden without a work permit, subject to applicable registration and residence requirements.
  • Non-EU/EEA citizens: Generally require a work permit or another residence status that authorises employment.
  • Salary requirements: From 1 June 2026, the general salary threshold for a new work permit is at least SEK 34,470 per month under the current published threshold. The salary must also meet the applicable collective agreement or industry standard.
  • Employer responsibilities: Employment terms, salary and insurance arrangements must satisfy the requirements for the relevant permit category. Additional rules may apply to specific occupations and permit types.
Payroll
  • Payroll Frequency: Salaries are commonly paid monthly, in accordance with the employment agreement.
  • Employer Registration and Reporting: Employers must register with the Swedish Tax Agency where required, withhold preliminary income tax and report salary and tax information through monthly employer declarations.
  • Taxable Income: Salary, bonuses, allowances and taxable benefits may be included in the employee’s taxable remuneration.
  • Employer Social Security Contributions: The standard rate is 31.42% of gross salary and taxable benefits for most employees. Different rates may apply according to age, eligibility for temporary reductions and the employee’s social security status.
  • Temporary Contribution Reduction: From 1 April 2026 to 30 September 2027, eligible employees aged 19–23 may qualify for a reduced rate of 20.81% on remuneration up to SEK 25,000 per month, with the standard rate applying above that amount.
  • Occupational Pension: Employers may also need to provide occupational pension and insurance benefits under collective agreements or individual employment arrangements.
Employment Contracts
  • Contract Types: Indefinite-term employment is the general rule. Fixed-term employment is permitted in specified circumstances under Swedish employment law.
  • Written Information: Employers must provide written information about essential employment conditions, including job duties, salary, working hours, employment type, leave and termination terms, within the statutory deadlines.
  • Probation Period: Generally up to six months. Employers must follow the applicable notification requirements when ending probationary employment.
  • Working Hours: Normal working time is generally limited to 40 hours per week. Statutory rules regulate overtime and rest periods, while collective agreements may provide additional or different terms within the applicable legal framework.
  • Notice Periods: The statutory minimum notice period is generally one month. Longer periods may apply depending on length of service, the employment agreement or a collective agreement.
  • Termination: Employers must comply with statutory requirements, including applicable grounds and procedures for dismissal. Collective agreements may also affect the process.
  • Minimum Wage: Sweden has no general statutory national minimum wage. Minimum pay rates are commonly set through collective agreements or established industry practice.
Employee Benefits
  • Annual Leave: Employees are entitled to at least 25 days of annual leave per year. The number of paid days depends on holiday-pay accrual and the applicable employment terms. Employees are generally entitled to four consecutive weeks of leave during June–August, subject to permitted exceptions.
  • Holiday Pay: Holiday pay is governed by the Annual Leave Act and may be supplemented or adjusted by collective agreements.
  • Sick Leave: Employers generally pay sick pay for the first 14 calendar days of an employee’s sickness absence, subject to statutory conditions and a qualifying-day deduction. Employees may then apply for sickness benefit from the Swedish Social Insurance Agency (Försäkringskassan).
  • Parental Leave: Eligible parents can share 480 days of parental benefit per child. Compensation is income-based for 390 days, with the remaining 90 days paid at a fixed minimum level. Statutory leave rights and benefit eligibility are separate considerations.
  • Public Holidays: Sweden observes national public holidays. The right to additional pay or time off on these days depends on the employment agreement and any applicable collective agreement.
  • Occupational Pension and Insurance: Occupational pension, life insurance and other supplementary benefits are common, particularly in workplaces covered by collective agreements.
Tax Overview
  • Tax Residency: Individuals who are resident in Sweden, have a habitual abode there or stay in the country for a continuous period of at least six months may be subject to Swedish tax-residency rules.
  • Residents: Generally taxed on worldwide income, subject to applicable exemptions and double taxation agreements.
  • Non-Residents: Generally taxed on Swedish-source income. Eligible non-residents may be taxed under the special income tax regime for non-residents (SINK).
  • Tax Year: 1 January – 31 December.
  • Personal Income Tax: Sweden levies municipal and regional income tax, with rates varying by municipality. An additional 20% state income tax applies to taxable earned income above the 2026 threshold of SEK 643,000, after the basic allowance has been deducted.
  • Employer Reporting: Employers generally deduct preliminary tax from salary and report remuneration and deductions to the Swedish Tax Agency.
  • Double Taxation Treaties: Sweden has double taxation agreements with numerous countries. The applicable agreement may affect how cross-border employment income is taxed.
Personal Income Tax
Annual Taxable Earned Income (SEK) State Income Tax Rate
Up to SEK 643,000 0%
Above SEK 643,000 20% on the portion exceeding SEK 643,000

Full Country Guide

How We Help You with Payroll & Compliance in Ghana

Want the complete PDF guide for

Sweden

? We share detailed country guides covering payroll, tax, and compliance — and we send new updates regularly. Just send an email to solutions@praxima.com, and we’ll send it straight to your inbox.

Page 1 of ?

Global Payroll Solutions for Every Market

Expanding beyond

Sweden

? Discover how we support compliance and payroll operations in 115+ countries.
Why Global Companies Trust Us for Sweden Payroll

Trusted Payroll Solutions Backed by Decades of Experience

With over 30 years of experience managing payroll and compliance across continents, we’re a trusted partner to enterprises in

Sweden

and beyond.

Icon of a headset and shield symbolizing payroll support and security

Support

Experts with deep local knowledge guide you through every step—onboarding, payroll, compliance—ensuring smooth operations in
Sweden
Icon of a handshake inside a shield symbolizing trust in payroll services

Trust

Global enterprises and Fortune 500s rely on us for consistent, compliant payroll delivery across complex, multi-country environments
Icon of a globe with outward arrows symbolizing scalable global payroll

Scalable

Our solutions adapt as you grow, whether you're hiring your first local employee or scaling an international team
Icon of a document and shield symbolizing payroll compliance and accuracy

Compliance

Stay ahead of legal changes. We ensure your payroll and employment practices remain fully compliant with

Sweden

's laws

Let’s Talk Sweden

Whether you need Payroll Outsourcing, Employer of Record services, or advanced Payroll Software, our experts are here to help you find the right solution. Contact us today for support with payroll, compliance, and hiring in

Sweden