Powering Payroll, Compliance & Workforce Management in Norway

Expand with confidence. Get local employment and payroll guidance backed by 30 years of experience.
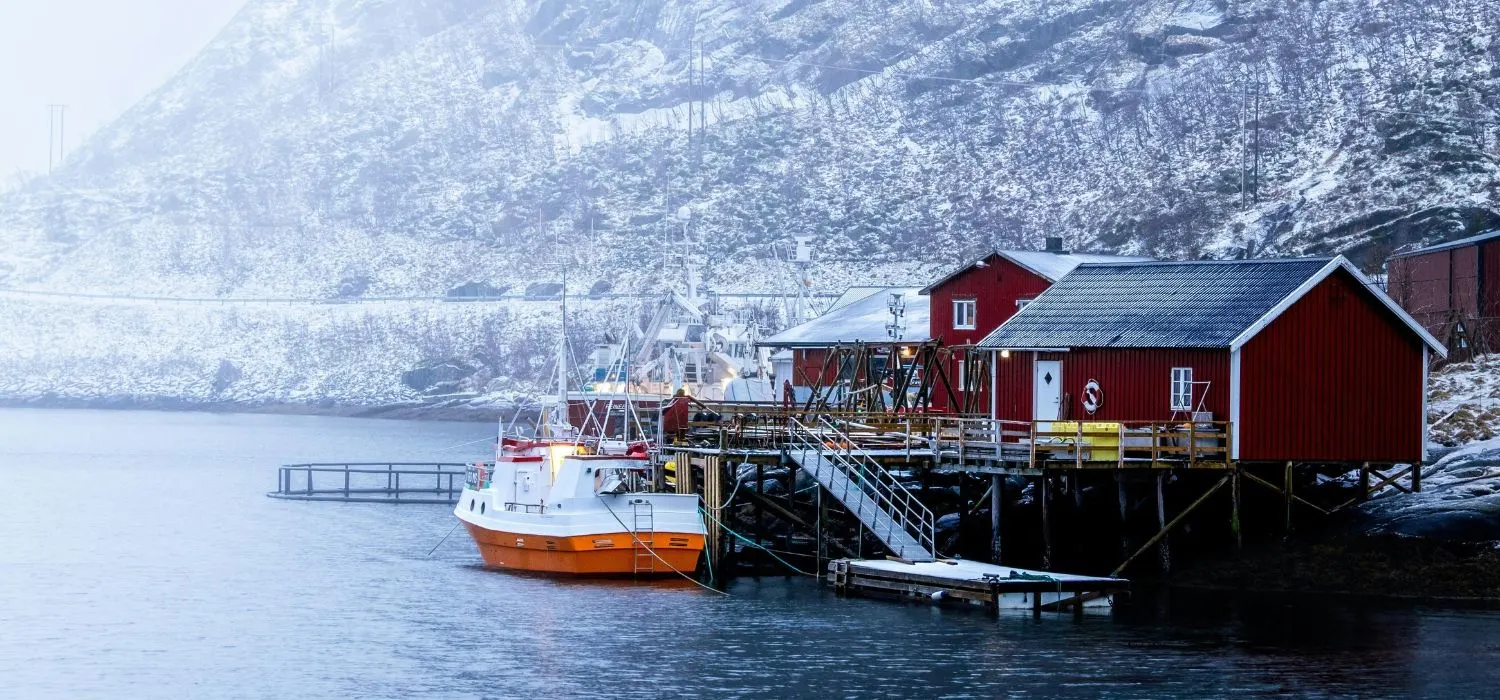
Norway at a Glance

Whether you're hiring your first employee or expanding an existing team, understanding the local employment landscape is essential. From visa requirements and statutory benefits to payroll taxes and regulatory oversight, this section provides a practical overview of what employers need to know to stay compliant and operate effectively in 

Norway
Work Permits & Visas

Foreign nationals may need a residence permit or other authorisation to work in Norway, depending on their nationality and employment status.

  • EU/EEA Citizens: Generally have the right to work in Norway without a work permit. Registration requirements apply to stays exceeding three months.
  • Non-EU/EEA Nationals: Generally need a residence permit that allows employment before starting work.
  • Skilled Workers: Eligible applicants may qualify for a skilled-worker residence permit based on their qualifications, job offer and other requirements.
  • Employer Responsibilities: Employers must verify the employee’s right to work and comply with applicable immigration and reporting requirements.
  • Permit Conditions: Employees must work within the conditions of their authorisation. Changes in role or employer may require additional approval.

Requirements vary according to nationality, job type and residence status. Employers should confirm the correct route before employment begins.

Payroll

Norwegian employers must operate payroll withholding, report employee remuneration and pay employer national insurance contributions.

  • Payroll Frequency: Monthly salary payments are common. Payment intervals and salary terms must be documented in the employment contract.
  • Income Components: Taxable remuneration may include salary, bonuses, allowances and benefits in kind.
  • Income Tax Withholding: Employers deduct tax in accordance with the employee’s tax deduction card and report payments through the applicable reporting system.
  • Employee National Insurance: The standard national insurance contribution rate on salary income is 7.6% for most employees aged 17–69 in 2026, subject to the applicable rules and thresholds.
  • Employer National Insurance: The standard rate is 14.1% in Zone I. Rates vary by geographical zone and certain industry or business circumstances.
  • Mandatory Pension: Employers generally need to provide an occupational pension scheme for eligible employees. Under the standard minimum scheme, employer contributions are generally at least 2% of qualifying salary.
  • Payroll Reporting: Employers report employment income, withholding tax and other relevant information through the monthly a-melding system.
  • Minimum Wage: Norway has no universal national minimum wage. Statutory minimum rates apply in specified sectors, including construction, cleaning, hospitality and certain transport industries.

The applicable employer contribution rate depends on the employer’s registered location and any relevant special rules.

Employment Contracts

Employment relationships are primarily governed by Norway’s Working Environment Act. Employers must provide written employment contracts containing the essential terms of the employment relationship.

  • Contract Types: Permanent employment is the general rule. Temporary employment is permitted only in specified circumstances under the legislation.
  • Probation Period: Generally up to six months. For temporary employment, the probation period cannot exceed half the duration of the employment.
  • Working Hours: Standard working time is generally limited to 9 hours per 24-hour period and 40 hours per seven-day period. Many workplaces agree to a 37.5-hour week.
  • Overtime: Overtime must meet statutory conditions and is generally paid at a premium of at least 40% above the ordinary hourly rate.
  • Notice Period: The statutory minimum is generally one month, with longer periods applying according to service length and age. A shorter notice period may apply during a valid probation period.
  • Termination: Employers must have a legally justified reason for dismissal and follow the applicable consultation and notice procedures.
  • Minimum Wage: Pay is generally agreed between the employer and employee, unless a statutory sector minimum or applicable collective agreement sets a higher requirement.

Employment contracts should specify the employee’s role, salary, working hours, holiday entitlement, holiday pay and any applicable probation or notice arrangements.

Employee Benefits

Norway provides statutory holiday entitlements and social insurance benefits. Employers may also provide additional benefits through collective agreements or company policies.

  • Annual Leave: At least 25 working days per year under the Holidays Act, counting Saturdays as working days. Employees aged 60 or older receive an additional six working days.
  • Holiday Pay: Employees generally accrue holiday pay based on remuneration earned in the previous calendar year. The statutory rate is normally 10.2%, rising to 12% where the employee is entitled to five weeks of holiday under an agreement.
  • Sick Leave: Eligible employees may receive sickness benefits. Employers generally cover the first 16 calendar days of qualifying sickness absence, after which the Norwegian Labour and Welfare Administration (NAV) may pay benefits.
  • Parental Leave: Parents may take leave in connection with birth or adoption. Eligible parents may receive parental benefits through NAV, subject to qualifying conditions and benefit limits.
  • Paternity and Partner Leave: Fathers and co-mothers may be entitled to leave and a quota of parental benefits, depending on the family’s eligibility and benefit arrangement.
  • Public Holidays: Public holidays and 1 May and 17 May are subject to specific statutory rules. Additional pay for working on public holidays may depend on legislation or collective agreements.
  • Occupational Pension: Employers generally must provide a qualifying occupational pension scheme, with minimum employer contributions commonly starting at 2% of qualifying salary.

The right to leave and the right to receive payment during leave are separate matters; benefit eligibility and payment levels depend on the applicable rules.

Tax Overview
  • Tax Residency: Individuals may become Norwegian tax residents based on the length of their stay. Generally, residence applies after more than 183 days in a 12-month period or more than 270 days in a 36-month period, subject to the detailed rules.
  • Residents: Generally taxed on worldwide income and wealth, subject to applicable exemptions and tax treaties.
  • Non-Residents: Generally subject to tax on specified Norwegian-source income.
  • Tax Year: 1 January – 31 December.
  • Ordinary Income Tax: The standard rate for individuals is 22% on ordinary income after eligible deductions. A reduced rate of 18.5% applies to eligible residents in the designated northern tax area.
  • Bracket Tax: A progressive additional tax applies to personal income above annual thresholds, with rates ranging from 1.7% to 17.8% in 2026.
  • National Insurance: The standard employee contribution rate on salary income is 7.6% for most employees aged 17–69 in 2026, subject to applicable rules.
  • Double Taxation Treaties: Norway has an extensive treaty network that may affect the tax treatment of cross-border employment income.

Norway’s overall tax burden depends on ordinary income tax, bracket tax, national insurance contributions, deductions and the employee’s individual circumstances.

Personal Income Tax
Annual Personal Income (NOK) Bracket Tax Rate
Up to NOK 226,100 0%
NOK 226,101 – NOK 318,300 1.7% on the portion within this bracket
NOK 318,301 – NOK 725,050 4.0% on the portion within this bracket
NOK 725,051 – NOK 980,100 13.7% on the portion within this bracket
NOK 980,101 – NOK 1,467,200 16.8% on the portion within this bracket
Above NOK 1,467,200 17.8% on the portion exceeding NOK 1,467,200

Full Country Guide

How We Help You with Payroll & Compliance in Ghana

Want the complete PDF guide for

Norway

? We share detailed country guides covering payroll, tax, and compliance — and we send new updates regularly. Just send an email to solutions@praxima.com, and we’ll send it straight to your inbox.

Page 1 of ?

Global Payroll Solutions for Every Market

Expanding beyond

Norway

? Discover how we support compliance and payroll operations in 115+ countries.
Why Global Companies Trust Us for Norway Payroll

Trusted Payroll Solutions Backed by Decades of Experience

With over 30 years of experience managing payroll and compliance across continents, we’re a trusted partner to enterprises in

Norway

and beyond.

Icon of a headset and shield symbolizing payroll support and security

Support

Experts with deep local knowledge guide you through every step—onboarding, payroll, compliance—ensuring smooth operations in
Norway
Icon of a handshake inside a shield symbolizing trust in payroll services

Trust

Global enterprises and Fortune 500s rely on us for consistent, compliant payroll delivery across complex, multi-country environments
Icon of a globe with outward arrows symbolizing scalable global payroll

Scalable

Our solutions adapt as you grow, whether you're hiring your first local employee or scaling an international team
Icon of a document and shield symbolizing payroll compliance and accuracy

Compliance

Stay ahead of legal changes. We ensure your payroll and employment practices remain fully compliant with

Norway

's laws

Let’s Talk Norway

Whether you need Payroll Outsourcing, Employer of Record services, or advanced Payroll Software, our experts are here to help you find the right solution. Contact us today for support with payroll, compliance, and hiring in

Norway