Powering Payroll, Compliance & Workforce Management in Argentina

Expand with confidence. Get local employment and payroll guidance backed by 30 years of experience.
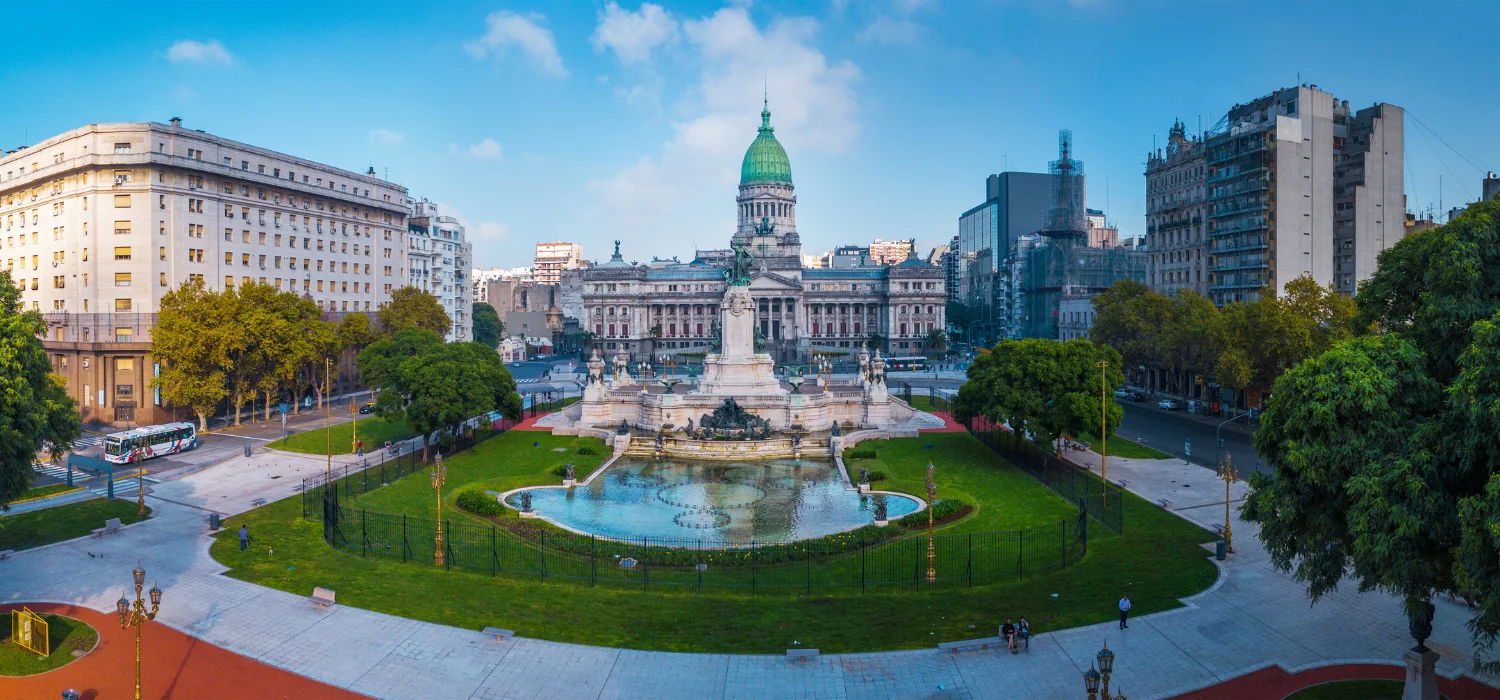
Argentina at a Glance

Whether you're hiring your first employee or expanding an existing team, understanding the local employment landscape is essential. From visa requirements and statutory benefits to payroll taxes and regulatory oversight, this section provides a practical overview of what employers need to know to stay compliant and operate effectively in 

Argentina
Work Permits & Visas
  • Foreign employees must hold appropriate immigration status to work legally in Argentina. Foreign nationals employed under a local employment relationship can apply for temporary residence as migrant workers.
  • Temporary Residence: A temporary residence permit for migrant workers is generally granted for one year and can be renewed. The application requires, among other documentation, a local employment pre-contract, employer CUIT registration and proof that the employer is registered with the immigration authorities. 
  • MERCOSUR Nationals: Citizens of MERCOSUR member and associated countries can generally obtain temporary residence for up to two years, renewable, providing a simplified route to working legally in Argentina. 
  • Employer Requirements: Employers hiring foreign workers must be appropriately registered and provide the required employment documentation to support the employee's immigration application. 
  • Permanent Residence: MERCOSUR nationals may generally qualify for permanent residence after two years of temporary residence, while nationals of other countries may qualify after three years, subject to the applicable requirements.
Payroll
  • Payroll Frequency: Salaries are generally processed monthly, with employers responsible for calculating salary, statutory deductions, social security contributions and applicable income tax withholding.
  • Income Components: Taxable employment income may include salary, bonuses, allowances, benefits and other remuneration arising from employment.
  • Employee Contributions: Employees generally contribute 11% towards the pension system, 3% towards INSSJP and 3% towards the health insurance system, giving a standard employee contribution of approximately 17%, before any additional applicable deductions.
  • Employer Contributions: Standard employer social security contributions are generally 18% or 20.4%, depending on the employer's classification and activity. A separate 6% employer contribution applies to the health insurance system under the current regime. Employers must also account for occupational risk insurance and other applicable payroll obligations.
  • Minimum Wage: The national minimum wage is ARS 391,200 per month from October 2026 for employees working a full legal working schedule, increasing to ARS 398,800 in November and ARS 406,400 in December 2026. 
  • Annual Bonus: Employees are entitled to the Sueldo Anual Complementario (SAC), commonly known as the 13th salary or aguinaldo, paid in two instalments in June and December. Each instalment is generally based on 50% of the employee's highest monthly remuneration during the relevant semester.
Employment Contracts
  • Contract Types: Employment is generally presumed to be for an indefinite period unless a fixed-term or other permitted contractual arrangement is properly established. Fixed-term contracts must meet statutory requirements and should generally be documented in writing. 
  • Probation: The standard probationary period for an indefinite-term employment contract is six months. Collective bargaining agreements may extend this to eight months for certain employers and up to one year for businesses with up to five employees. 
  • Working Hours: The statutory maximum is generally 8 hours per day or 48 hours per week. Overtime is normally paid at a premium of at least 50%, increasing to 100% for work performed on public holidays. 
  • Minimum Wage: Employees working a full legal working schedule must receive at least the applicable national minimum wage, although collective bargaining agreements may establish higher sector-specific minimums.
  • Notice Periods: Employees generally provide 15 days' notice when resigning. Employer notice is one month for employees with up to five years' service and two months for employees with more than five years' service. No notice is required during the probationary period.
  • Termination: Employers may terminate employment for statutory reasons or without cause, subject to the applicable notice and severance requirements.
  • Severance: For dismissal without cause after the probationary period, statutory severance is generally calculated at one month's salary for each year of service or fraction exceeding three months, subject to the statutory calculation rules and applicable limits. 
  • Collective Bargaining: Collective bargaining agreements are widely used in Argentina and may provide employment terms and benefits that differ from the statutory minimums.
Employee Benefits
  • Annual Leave: Paid annual leave depends on length of service: 14 calendar days for less than 5 years, 21 days for 5–10 years, 28 days for 10–20 years and 35 days for more than 20 years of service. 
  • Sick Leave: Paid sick leave is generally available for up to 3 months for employees with less than 5 years' service and up to 6 months for employees with more than 5 years. Where the employee has family dependants, these periods can increase to 6 and 12 months respectively. 
  • Maternity Leave: Maternity leave is 90 calendar days, generally divided between the period before and after childbirth. The social security system provides the maternity benefit during the statutory leave period, subject to the applicable requirements. 
  • Paternity Leave: The statutory general entitlement is 2 paid calendar days for the birth of a child. Collective bargaining agreements may provide more generous leave. 
  • Annual Bonus: Employees receive the statutory Sueldo Anual Complementario, paid in two instalments each year. 
  • Public Holidays: Employees are entitled to statutory public holidays and applicable paid rest days, with special remuneration rules applying where employees work on certain holidays or rest days.
  • Social Security: Registered employees are covered by Argentina's social security framework, including pension, health insurance, family allowance and unemployment-related systems, together with occupational risk coverage.
Tax Overview
  • Tax Residency: Foreign individuals generally become Argentine tax residents once they obtain permanent residence or, where permanent residence has not been obtained, after having remained in Argentina under temporary authorisations for 12 months.
  • Residents: Argentine tax residents are generally subject to Argentine income tax on worldwide income, subject to applicable exemptions, deductions and international tax treaty provisions.
  • Non-Residents: Non-residents are generally subject to Argentine tax on Argentine-source income.
  • Tax Year: January 1 – December 31.
  • Personal Income Tax: Argentina operates a progressive personal income tax system. For employment income, the applicable 2026 scale ranges from 5% to 35%, with the tax calculated progressively over the employee's net taxable income. The scale and personal deductions are adjusted periodically based on the statutory inflation adjustment mechanism. 
  • Tax Withholding: Employers are responsible for calculating and withholding applicable income tax from employees' salaries and complying with the relevant reporting and payment requirements.
  • Double Taxation Treaties: Argentina has double taxation agreements with a number of countries, which may affect the taxation of cross-border employment income.
Personal Income Tax
Net Taxable Income (ARS) Tax Payable Rate on Excess
Up to ARS 2,168,491.89 ARS 0 5%
ARS 2,168,491.90 – ARS 4,336,983.77 ARS 108,424.59 9%
ARS 4,336,983.78 – ARS 6,505,475.65 ARS 303,588.86 12%
ARS 6,505,475.66 – ARS 9,758,213.49 ARS 563,807.89 15%
ARS 9,758,213.50 – ARS 19,516,426.99 ARS 1,051,718.57 19%
ARS 19,516,427.00 – ARS 29,274,640.48 ARS 2,905,779.13 23%
ARS 29,274,640.49 – ARS 43,911,960.73 ARS 5,150,168.23 27%
ARS 43,911,960.74 – ARS 65,867,941.10 ARS 9,102,244.70 31%
Above ARS 65,867,941.10 ARS 15,908,598.62 35%

Full Country Guide

How We Help You with Payroll & Compliance in Ghana

Want the complete PDF guide for

Argentina

? We share detailed country guides covering payroll, tax, and compliance — and we send new updates regularly. Just send an email to solutions@praxima.com, and we’ll send it straight to your inbox.

Page 1 of ?

Global Payroll Solutions for Every Market

Expanding beyond

Argentina

? Discover how we support compliance and payroll operations in 70+ countries.

Why Global Companies Trust Us for Argentina Payroll

Trusted Payroll Solutions Backed by Decades of Experience

With over 30 years of experience managing payroll and compliance across continents, we’re a trusted partner to enterprises in

Argentina

and beyond.

Icon of a headset and shield symbolizing payroll support and security

Support

Experts with deep local knowledge guide you through every step—onboarding, payroll, compliance—ensuring smooth operations in
Argentina
Icon of a handshake inside a shield symbolizing trust in payroll services

Trust

Global enterprises and Fortune 500s rely on us for consistent, compliant payroll delivery across complex, multi-country environments
Icon of a globe with outward arrows symbolizing scalable global payroll

Scalable

Our solutions adapt as you grow, whether you're hiring your first local employee or scaling an international team
Icon of a document and shield symbolizing payroll compliance and accuracy

Compliance

Stay ahead of legal changes. We ensure your payroll and employment practices remain fully compliant with

Argentina

's laws

Let’s Talk Argentina

Whether you need Payroll Outsourcing, Employer of Record services, or advanced Payroll Software, our experts are here to help you find the right solution. Contact us today for support with payroll, compliance, and hiring in
Argentina